How money moves: where your money sits and what each event does
Every place your money sits in Otura — each drawer, the safe, the bank, card takings, what customers and suppliers owe, staff, VAT and your own capital — and what each everyday event moves, with the accounts for your accountant.
Checked against the product on 25 October 2026
Otura keeps your books in dollars. Every place money can sit is an account in your chart of accounts, and the cash you can count — a drawer, the safe, the bank — is also a box on FinanceAccountingCash & BankTreasury, which shows what each one holds. Each sale, drop, payout, transfer and count moves money from one place to another, and Otura writes that move in the books by itself. This page says where the money sits, and what each event moves. When to do what is in Your money routine.
Where your money sits
| Place | What it is | Account |
|---|---|---|
| Each till’s drawer | The dollars in that till. Made for each register when the chart is seeded, or when a register is added later. | 5100NN, named after the register (Register 1 drawer). A register set to Shared cash account (Cash Register) uses 5100 Cash Register. |
| Each till’s lira drawer | The lira in that till, kept apart from the dollars. Only for a business in dollars that takes lira. | 5105NN (Register 1 drawer - LBP), or 5105 Cash Register - LBP |
| The safe | Where drops go and pay ins come from. A box you add yourself. | 5110 Safe / Vault; 5115 Safe / Vault - LBP for lira |
| The bank | Your bank accounts. A box you add yourself. | 5120 Bank Account - USD, 5130 Bank Account - LBP |
| Card takings | Card sales, until the card processor pays them into the bank. | 5300 Card Receivable; 5305 Card Receivable - LBP for card sales charged in lira |
| Payouts waiting | Cash paid out of a drawer at the till, until someone says what it was for. | 5140 Cash Payouts - Unclassified |
| What customers owe | Sales on account; cash on delivery and web orders not yet collected; credit a customer holds after an exchange. | 4110 Accounts Receivable, 4111 COD Receivable, 4190 Customer Exchange Credits (owed to the customer) |
| What you owe suppliers | Bills not yet paid; stock received whose bill has not come. | 4210 Accounts Payable, 4215 Goods Received Not Invoiced |
| What you owe staff | Approved payroll not yet paid, and what it holds back for NSSF, salary tax and end of service. | 4520 Net Salaries Payable, 4510 NSSF Payable, 4440 Payroll Tax Payable (R10), 4530 End-of-Service Indemnity Payable |
| VAT | VAT charged on sales, less VAT paid on purchases you recover. | 4420 VAT Output / Payable, 4410 VAT Input |
| Your own money in the business | What the owners put in, and the profit the business has kept. | 1110 Paid-in Capital, 1120 Opening Balance Equity, 1210 Retained Earnings, 1220 Current Year Earnings |
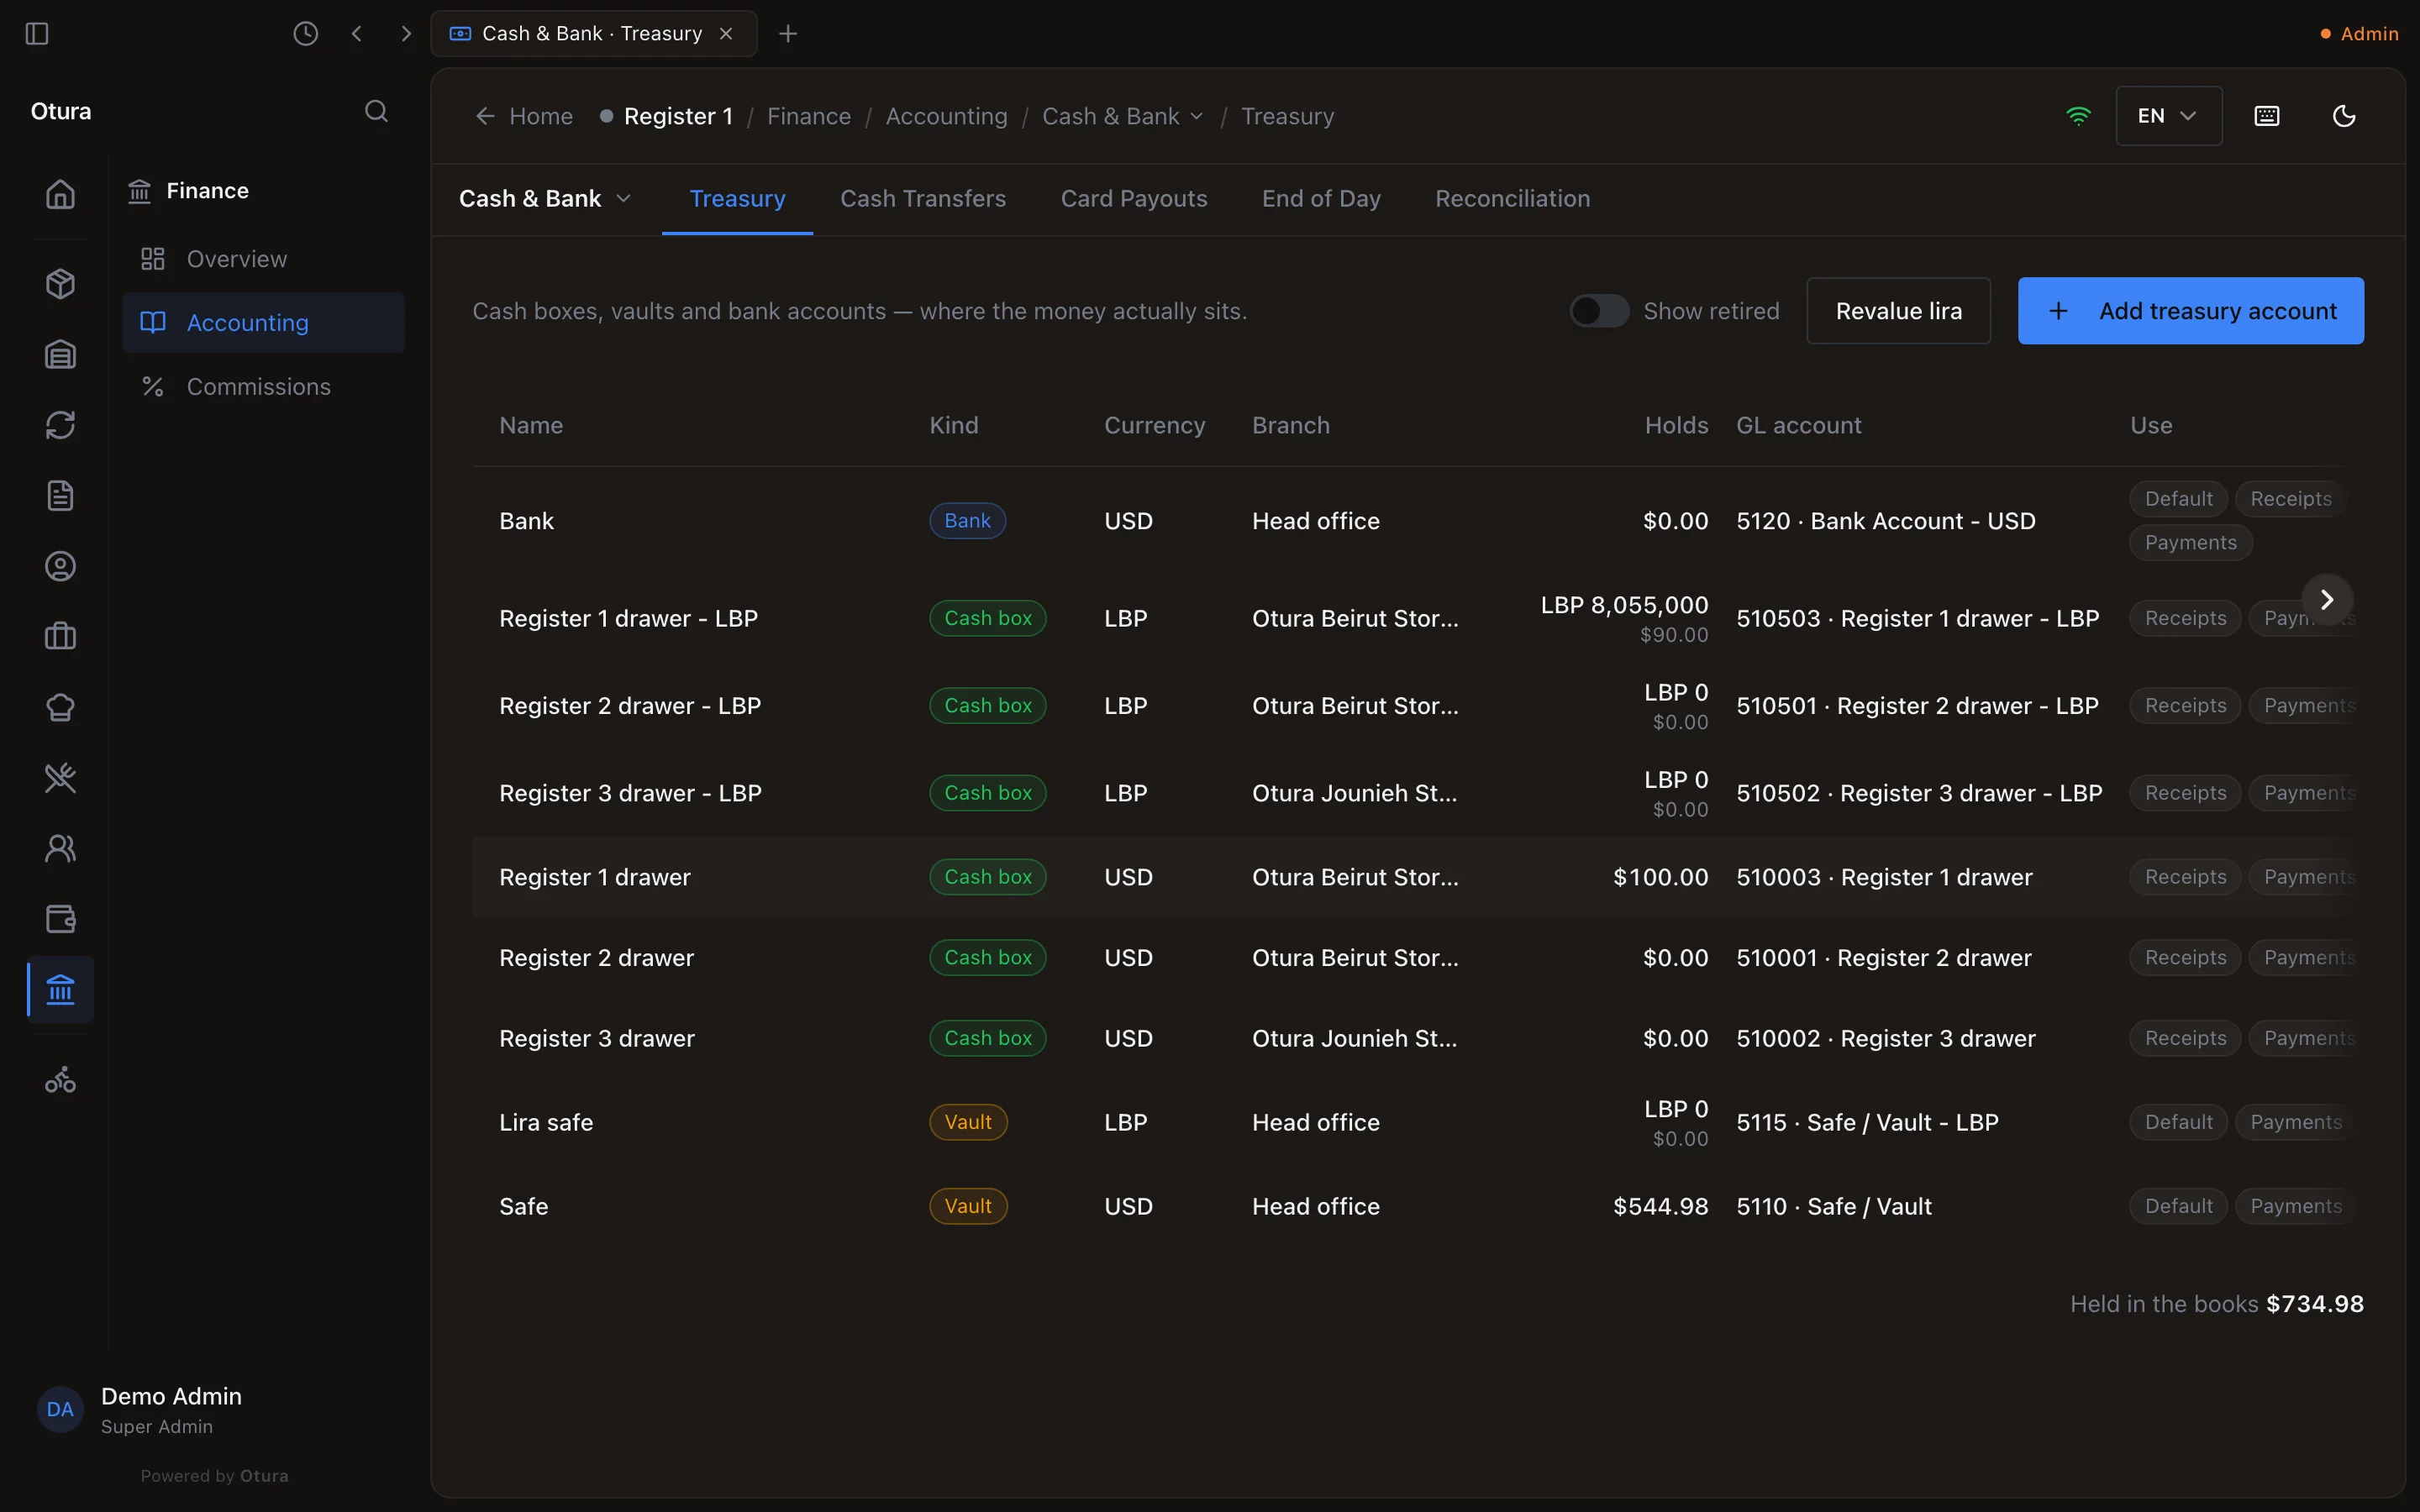
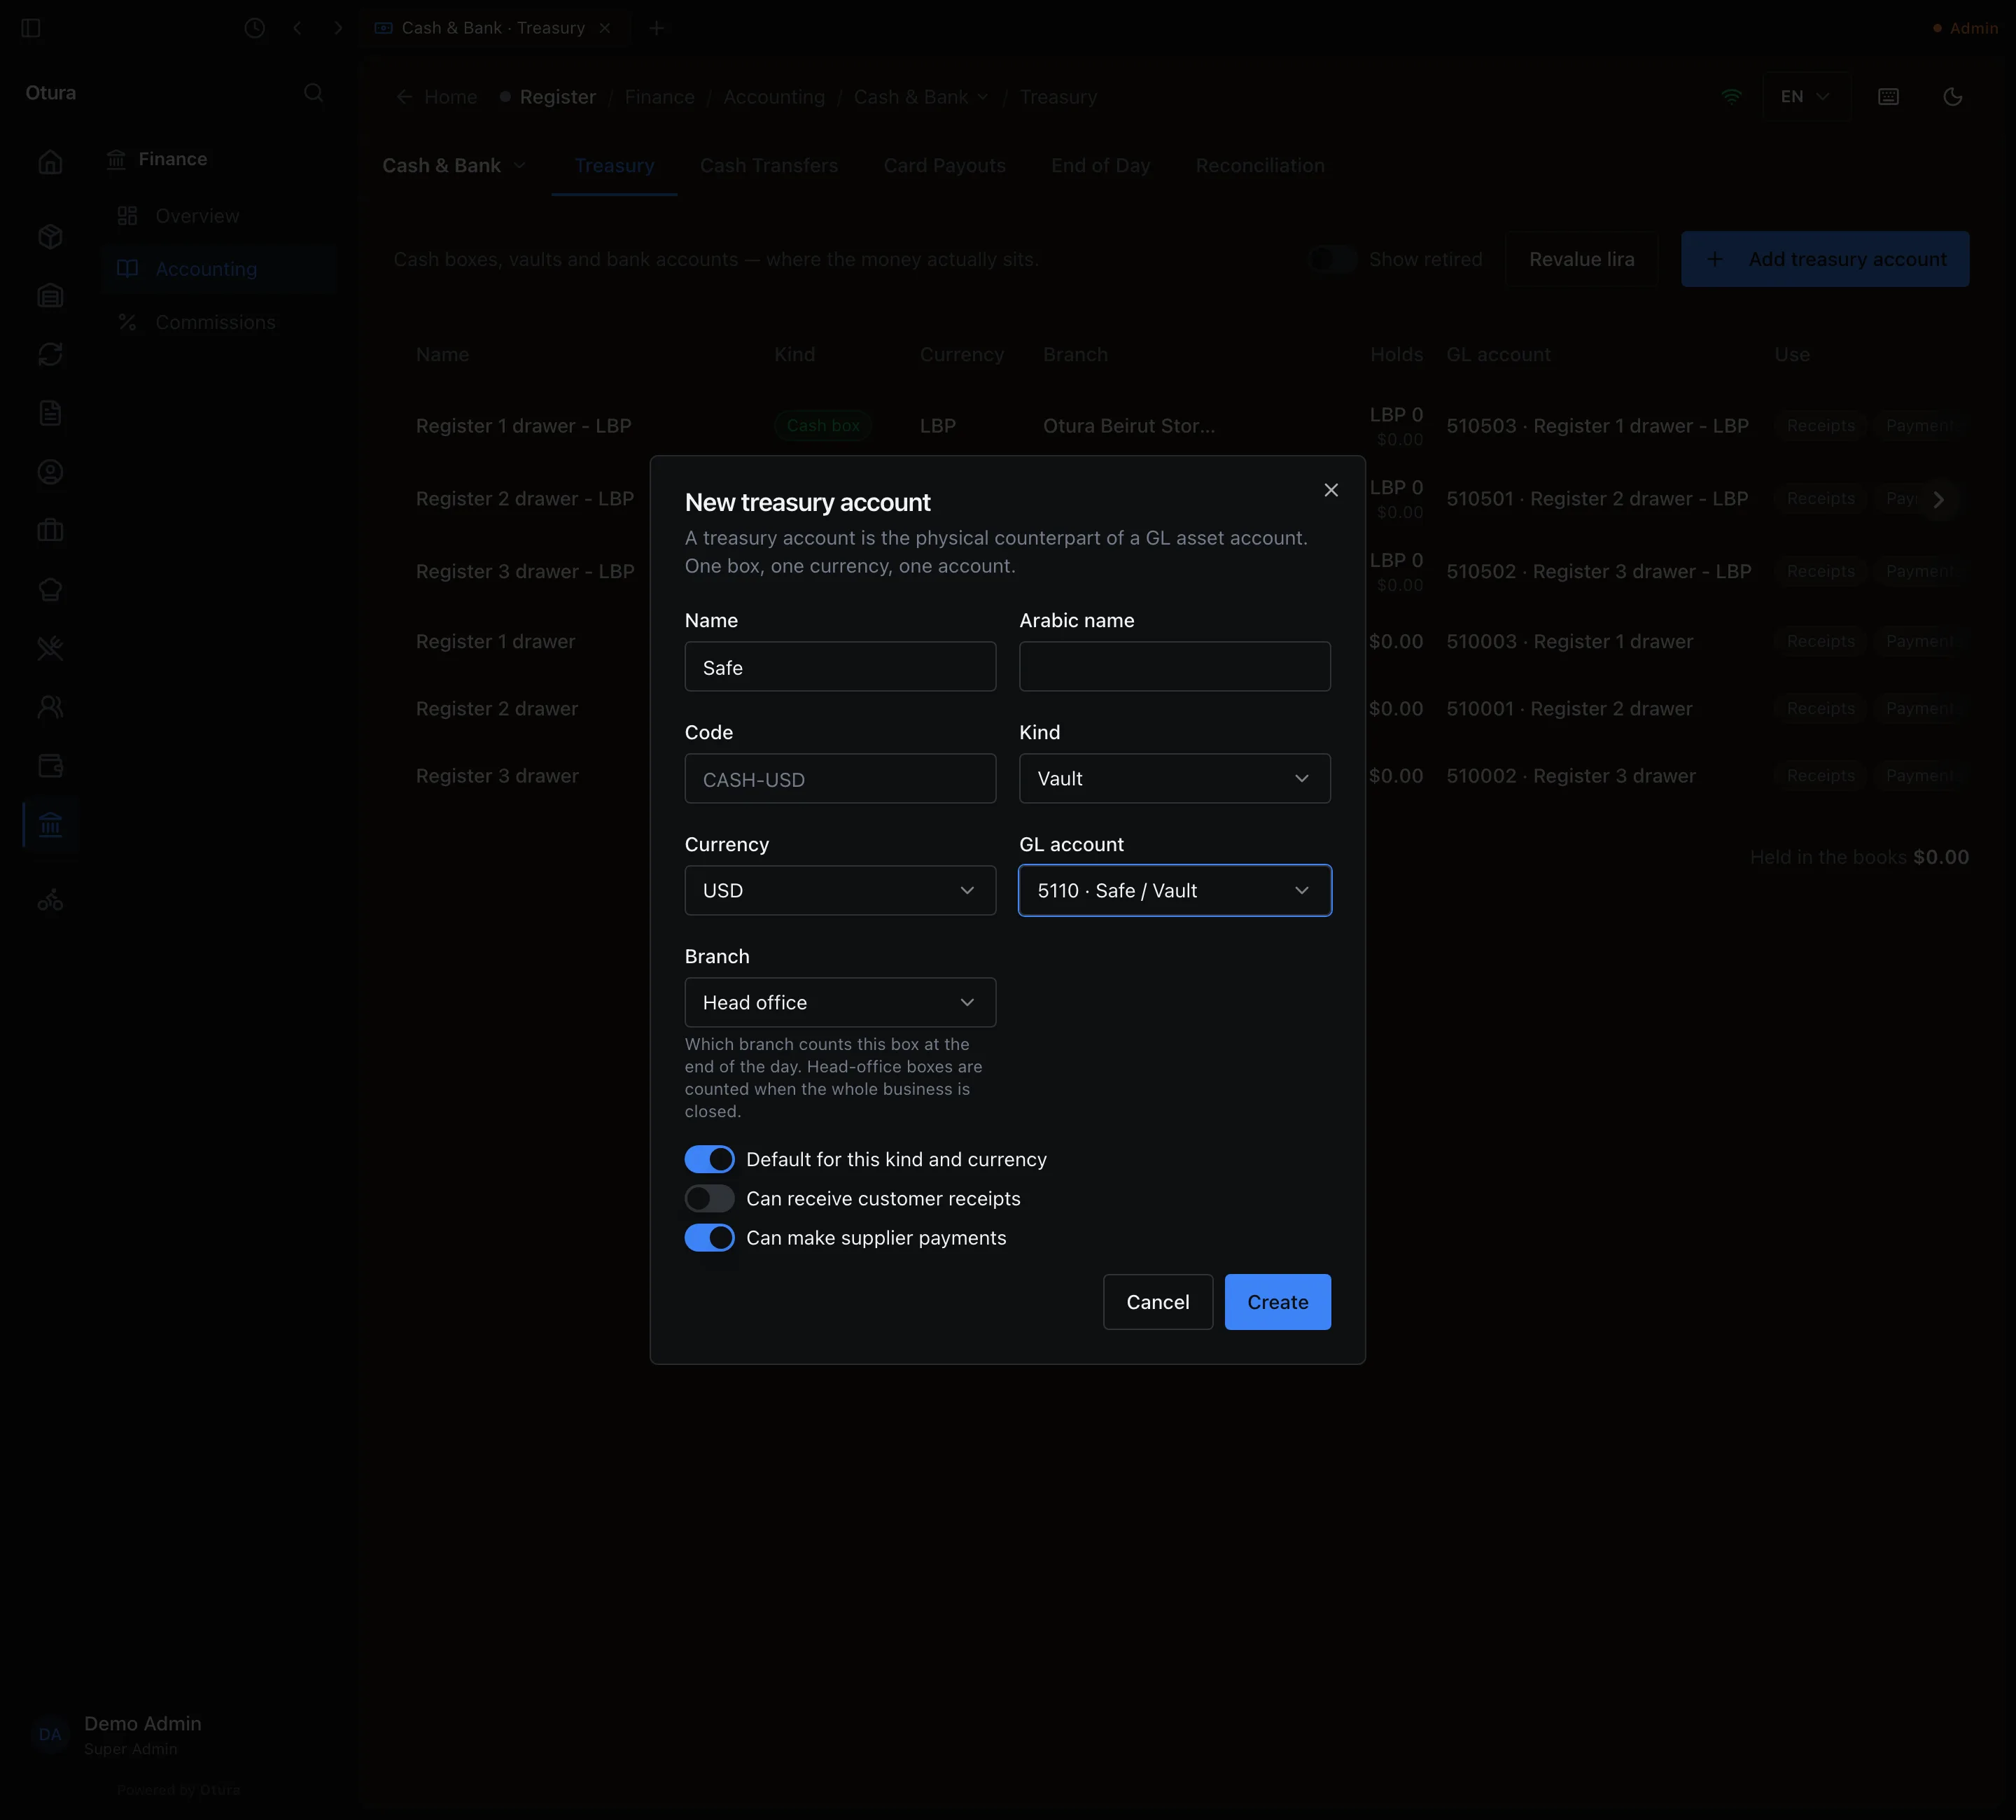
Seeding the chart makes each till's drawer boxes, at the register's branch. It makes no safe and no bank box: add them with Add treasury account, choosing the Kind (Vault for a safe, Bank for a bank account), the Currency, the GL account and the Branch. Put your dollar safe on 5110 · Safe / Vault and your lira safe on 5115 · Safe / Vault - LBP, so the drops that already landed there are in it (see Cash and bank).
What each everyday event does
In the table, the money moves from the place on the right to the place on the left. The last two columns are the entry Otura posts, for your accountant. "The drawer" is that till's drawer in the currency the money was in; "the safe" is the safe of the drawer's branch, or your default safe if the branch has none.
At the till
| Event | What happens to your money | Debit | Credit |
|---|---|---|---|
| Open Shift | Nothing moves. The float you type is what the shift expects to start with. | — | — |
| The float check: Record it | The float came from the safe (or went back to it). | The drawer | The safe |
| A cash sale | The drawer gains what the customer paid, less any change. | The drawer (the lira drawer for lira) | 7010 Sales Revenue - POS, 4420 VAT Output / Payable |
| A card sale | Card takings grow until the processor pays out. | 5300 (5305 when charged in lira) | The same |
| A sale on account or cash on delivery | The customer owes it. | 4110, or 4111 for cash on delivery | The same |
| The goods that left | Stock goes down by what they cost. | 6010 Cost of Goods Sold | 3100 Merchandise Inventory |
| Loyalty points used | The points pay part of the sale. | 7910 Sales Discounts | The sale |
| A return | The money goes back the way the sale was paid, or becomes the customer’s credit. | 7900 Sales Returns, 4420 | The drawer, card, 4110, or 4190 for an exchange credit |
| A void | The sale is undone, on the day of the void; the cash leaves the drawer of the till that voided it. | The sale’s entry, reversed | |
| Cash Drop | Cash goes from the drawer to the safe. | The safe | The drawer |
| Pay In | Cash comes from the safe into the drawer. | The drawer | The safe |
| Payout | Cash leaves the drawer for an expense. It is not an expense yet: see below. | 5140 Cash Payouts - Unclassified | The drawer |
| A driver hands in cash | What the driver collected, less the fee they kept, comes into the drawer. | The drawer, in dollars | 4111 |
| Shift close, drawer short | The missing cash is a cost. | 6700 Cash Shortage | The drawer |
| Shift close, drawer over | The extra cash is income. | The drawer | 7700 Cash Overage |
A shift that closes exactly posts nothing. A dollar difference and a lira difference are booked each on their own drawer.
In the back office
| Event | What happens to your money | Debit | Credit |
|---|---|---|---|
| A Cash Transfer | Money moves between two boxes of one currency: drawer to safe, safe to bank. | The box it went into | The box it came out of |
| An Exchange | Lira for dollars, or dollars for lira, between two boxes. | The box it went into | The box it came out of; the difference to 6600 Exchange Loss or 7600 Exchange Gain |
| End of Day, a box short | The count is less than the books. | 6700, one line for the day | Each short box |
| End of Day, a box over | The count is more than the books. | Each over box | 7700, one line for the day |
| The card processor pays out | Card takings reach the bank, less the fee. | The bank, and 6250 Bank Charges for the fee | 5300 or 5305 |
| A supplier bill | You owe the supplier. | 4215 for received goods (6015 for a bill with no stock), 4410 when you recover VAT | 4210 Accounts Payable |
| A supplier payment | Money leaves the safe or the bank. | 4210 | The box paid from |
| A customer pays what they owe | Money comes into a box. | The box | 4110 |
| The VAT return is remitted | VAT is paid to the Ministry of Finance. | 4420 | 4410, and the box paid from for the rest |
| Payroll is approved | The month’s pay becomes a cost and a debt to staff. | 6310 Wages & Salaries, 6320 Employer NSSF Contributions, 6330 End-of-Service Indemnity Expense | 4520, 4510, 4440, 4530 |
| A month is closed | Lira boxes are brought to that month’s last rate. | Each lira box that gained, or 6600 | 7600, or each lira box that lost |
| The year is closed | The year’s profit or loss moves into your equity. | Every income account | Every expense account; the difference to 1210 Retained Earnings |
End of Day books shortages and overages separately: a box $5 short and another $5 over is $5 in Cash Shortage and $5 in Cash Overage, not nothing. A day where every box is exact posts nothing. How a transfer, an exchange and the count work is in Cash and bank.
Payouts
A payout at the till takes cash out of the drawer, and the shift expects that much less. In the books it waits on 5140 Cash Payouts - Unclassified, an asset, because Otura does not know what it bought. The till asks for a reason so that someone can later say: the reasons are in the shift report's Cash moved in and out and the till's Drawer Event Log.
What Otura does not book
Some money leaves or enters the business with no screen that books it. Each needs a journal entry from you, with New Entry, until Otura does it.
| What happened | What Otura does | The entry to post yourself |
|---|---|---|
| You paid the salaries | Payroll › Mark Paid changes the run’s status only. 4520 keeps growing. | Debit 4520 Net Salaries Payable, credit the box paid from |
| You paid NSSF or an end-of-service indemnity | Nothing: no screen takes them off 4510 or 4530. | Debit 4510 (or 4530), credit the box paid from |
| You paid commission | Commissions › Approve and Mark as Paid change statuses only. Commission is never in the books. | Debit an expense account you add for commission, credit the box paid from |
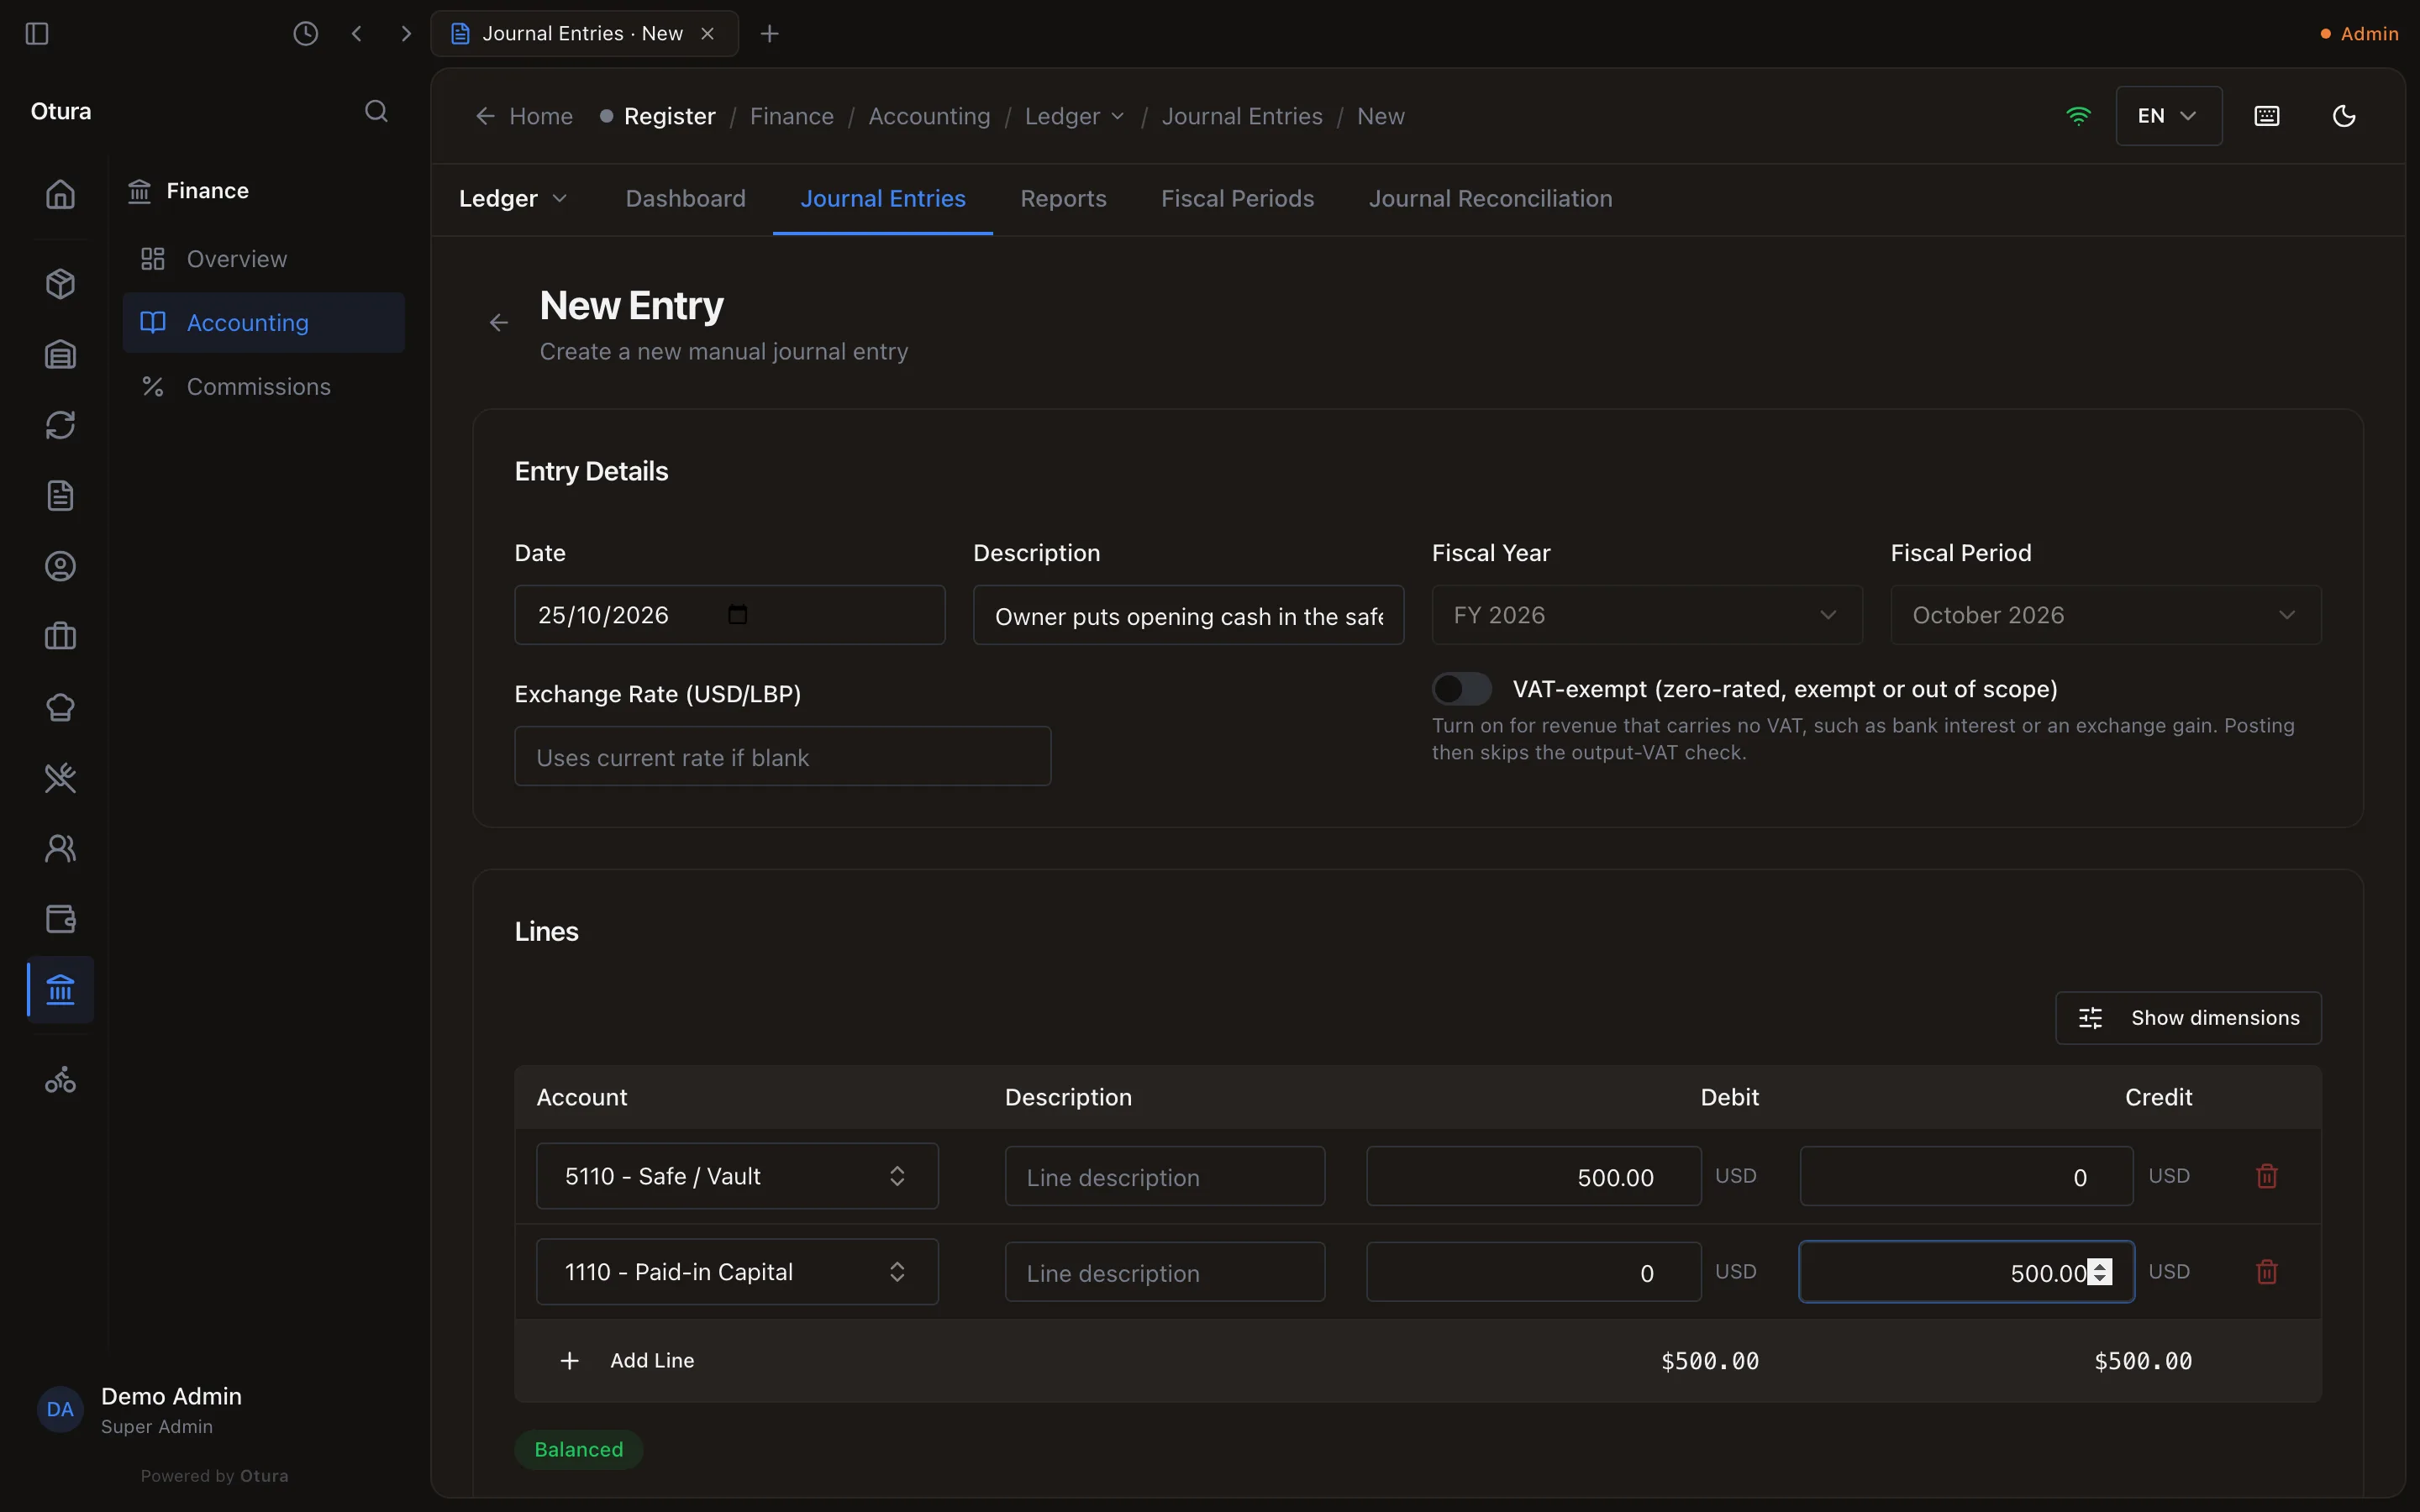
| You put money into the business | Nothing: there is no screen for capital. | Debit the box it went into, credit 1110 Paid-in Capital |
| You took money out for yourself | Nothing: there is no screen, and no drawings account. | Debit 1210 Retained Earnings, or an equity account you add for drawings; credit the box it came out of |
Dollars and lira
The books are in dollars. A lira account — a lira drawer, the lira safe, a lira bank account — also keeps the lira that actually changed hands, so its lira balance is what you should find when you count it. The dollar value of lira depends on which rate was used:
| What | The rate it is valued at |
|---|---|
| A sale, its return and its void | The rate the sale was rung at, kept with the sale. Changing the rate never changes a past sale. |
| A lira drop, payout or pay in, and a shift’s lira difference | Today’s rate when it is recorded |
| End of Day | Today’s rate |
| A month close | Each lira box is brought to the rate at the end of the month’s last day; the difference is 7600 Exchange Gain or 6600 Exchange Loss. Revalue lira on Treasury does the same at today’s rate, at any time. |
So the same lira can be worth different dollars in two places, and the month close brings the boxes back in line. How to set the rate is in Exchange rates.
Cash rounding
When cash is rounded, the sale is booked at what was actually paid. A $62.50 sale paid in lira at 89,500 is LBP 5,593,750; rounded to the nearest 5,000, the customer pays LBP 5,595,000, which is $62.51. The sale is a $62.51 sale, its VAT is worked out on $62.51, and the lira drawer gains LBP 5,595,000. There is no rounding account: the cent is in the sale's revenue and VAT. The setting is in Cash rounding.
Where to see it
- What each box holds: FinanceAccountingCash & BankTreasury.
- Every entry on one account: the General Ledger in Financial reports.
- A shift's cash: the shift report (Closing a shift); a day's: End of Day (Cash and bank).